First Home · Charlotte

Is Charlotte, NC Still Affordable to Buy a Home In? (2026)

Is Charlotte, NC still affordable to buy a home in? What changed since 2019, where affordability actually lives now, and how to test it against your budget.
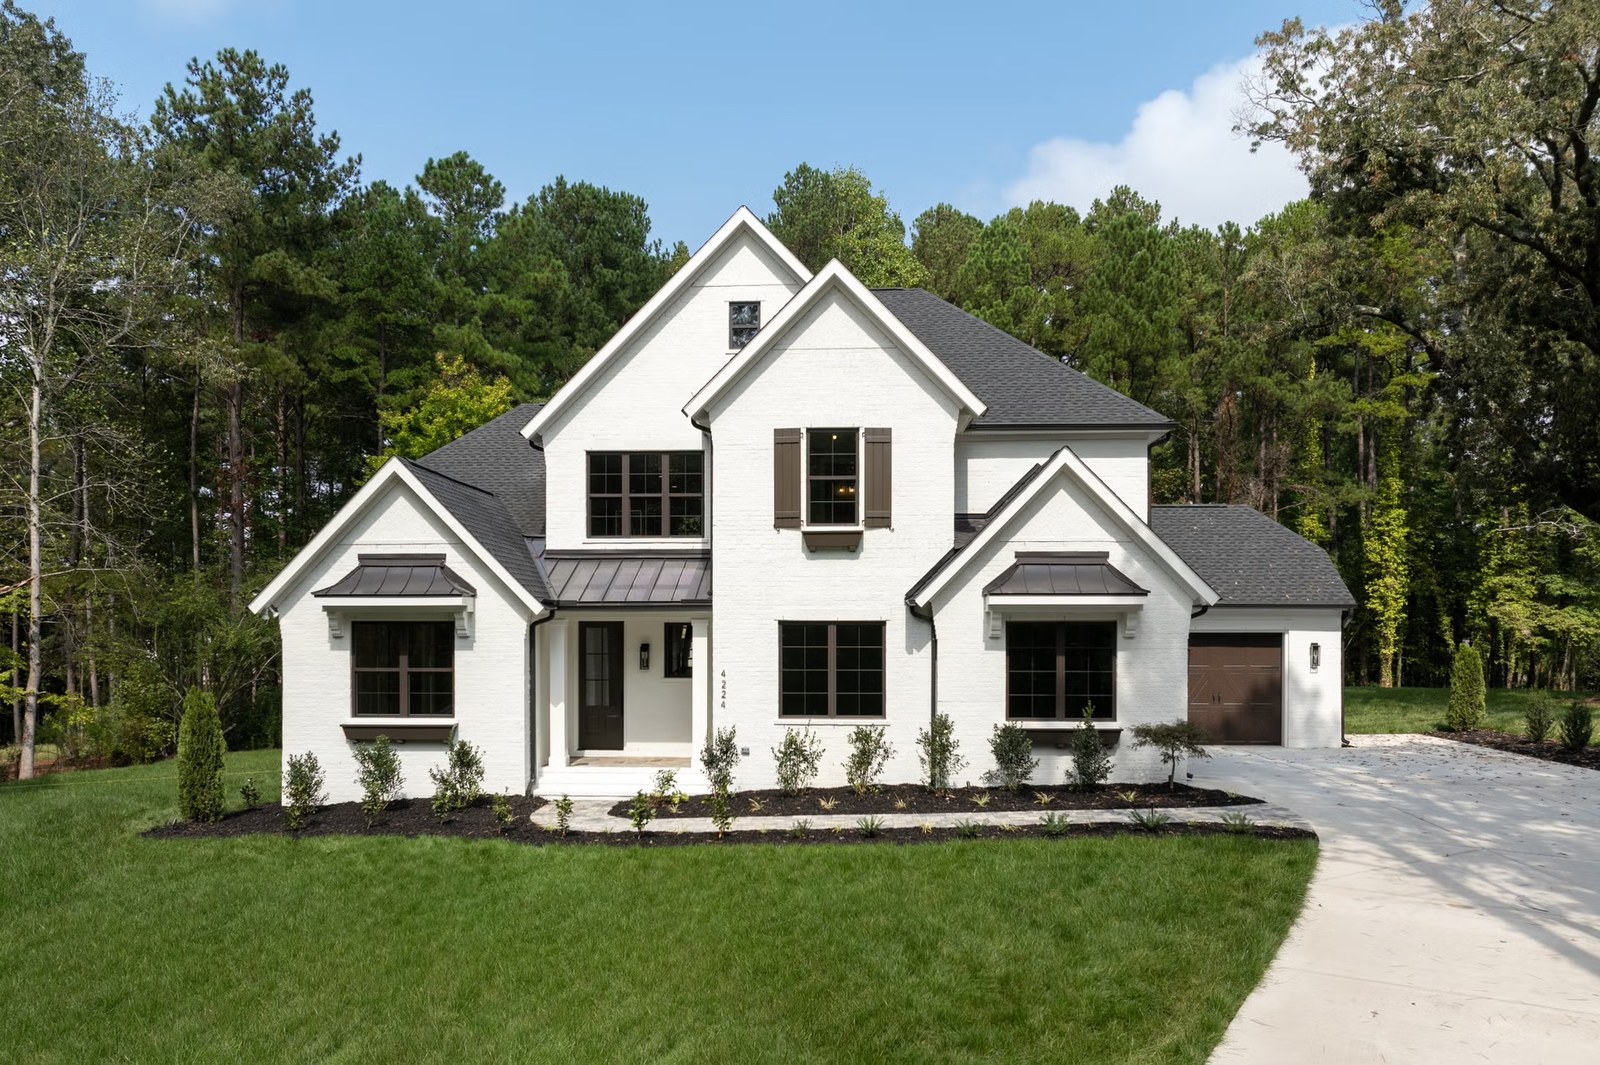
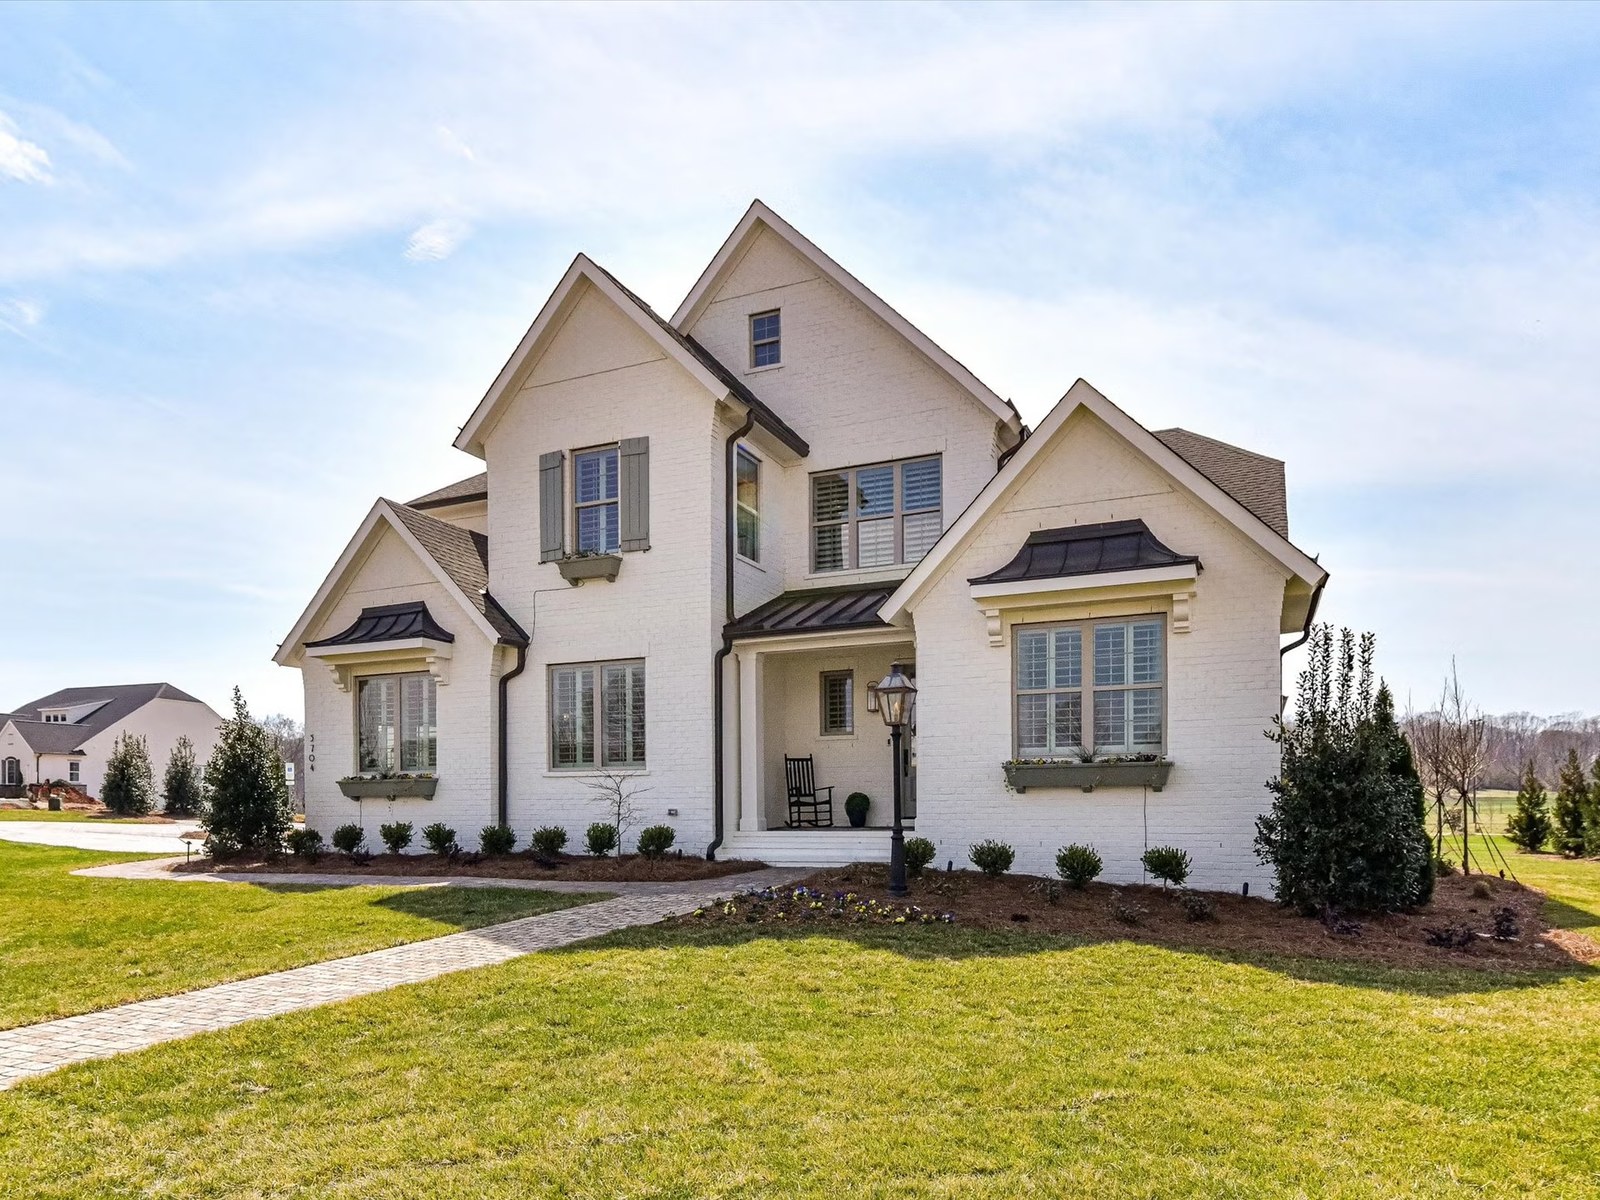
A cream stucco-and-stone two-storey home on an open lawn
The short answer

Is Charlotte still affordable? It depends entirely on your baseline. Compared to New York, Los Angeles, Boston, or D.C., yes — your housing dollar still stretches meaningfully further here, and that gap is why people keep arriving. Compared to the Charlotte of 2019, no — years of rapid growth have permanently repriced the city, and the version longtime locals remember is gone. Affordability hasn't vanished; it has moved. It now lives in specific trade-offs — drive time, square footage, home age, attached vs. detached — and knowing which trade-off you can live with matters more than any headline.

Is Charlotte, NC still affordable to buy a home in — compared to what?

"Is Charlotte still affordable" is really two different questions wearing the same words, and they have opposite answers. So let me give you both, plainly.

If your baseline is a high-cost coastal market — yes. Buyers arriving from New York, New Jersey, California, Boston, or D.C. still experience Charlotte as a genuine repricing of their life. The same monthly housing cost that bought a commute and a compromise there buys space, light, a yard, and a shorter Tuesday here. That math is why the moving trucks haven't stopped, and as of mid-2026 it's still true. Not as dramatically true as it was a few years ago — the gap has narrowed — but true.

If your baseline is the Charlotte of 2019 — no. The city that people remember, where a solid house in a well-located neighborhood felt casually attainable on an ordinary income, has been repriced. Years of in-migration, constrained inventory, and construction costs did what they do everywhere they happen together. Prices stepped up and, for the most part, stayed up. Anyone telling you Charlotte is still cheap is either selling something or hasn't looked lately.

Both of these are the truth. Which one applies to you depends on where you're standing — and that's the honest starting point most affordability content skips.

What actually changed since 2019?

You don't need a chart to understand what happened; you need the mechanism. Charlotte spent the last several years as one of the country's fastest-growing metros — a banking center with a livable climate, absorbing arrivals faster than it could build homes for them. Demand grew quickly. Inventory didn't keep pace. Prices moved the only direction that combination allows.

Three shifts matter for how affordability feels now:

  1. The entry point moved. The lowest rung of the ladder — the modest, well-located starter home — is the segment that repriced hardest, because it's where the most buyers compete. The homes still exist; the casual access to them doesn't.
  2. The monthly cost moved more than the price did. With rates in the mid-sixes as of mid-2026, the same price carries a heavier payment than it did in the low-rate era. Buyers comparing today's payment to a 2020 payment are comparing two different financial worlds. I walk through the full monthly picture — taxes, insurance, dues, the works — in what the whole cost of living in Charlotte looks like.
  3. The geography of value shifted outward and sideways. What a given budget bought close-in five years ago, it now buys with a longer drive, a smaller footprint, or an older roof. The value didn't disappear. It relocated.

None of this is unique to Charlotte — it's the story of nearly every growing Sun Belt metro. But Charlotte's version is real, and pretending otherwise would waste your time.

Where does affordability actually live in Charlotte now?

Here's the part that headlines can't do, because it isn't one answer — it's a trade-off map. Affordability in Charlotte in 2026 isn't a place; it's an exchange. At every budget, you can still buy well here. What changes is what you trade to do it. (And to be clear about what this map is not: it's a map of budgets and trade-offs, never of who lives where. That's both the law and the only honest way to do this.)

  1. At the entry level, affordability lives in the townhome and the condo, in newer communities farther from the center, and in older homes that need your patience and a renovation budget. The trade is usually attached walls or drive time — not quality of life. Some of the best-lived lives I've seen started in an unglamorous townhome bought with margin.
  2. In the middle bands, affordability lives in choosing your one non-negotiable and flexing everything else. Close-in and spacious and updated is the combination that's been repriced out of reach for most budgets. Close-in and smaller? Available. Spacious and twenty-five minutes out? Available. Updated but on a busier street? Available. The buyers who feel squeezed are usually the ones refusing to rank their priorities.
  3. At the higher bands, the affordability question inverts: it's less "can I buy here" and more "am I paying a premium for the right things?" Value at this level lives in judgment — lot, light, build quality, long-term desirability — not in finding a deal.

If you want to see this concretely, what $700K actually buys across Charlotte makes the trade-off map visible price band by price band.

Is Charlotte still affordable for you?

This is the version of the question that actually matters, and it's answerable. Three honest checks:

  1. Run your baseline. If you're relocating from a higher-cost market, price your current monthly housing cost against what that same number carries here. That comparison — not the "Charlotte got expensive" discourse — tells you whether this move is an upgrade. If you're already local, the question isn't 2019 nostalgia; it's whether today's payment fits today's income with margin left over. My honest affordability math walks that calculation properly — comfort number, not approval ceiling.
  2. Name your trade-off before you shop. Decide which exchange you can live with — drive time, square footage, home age, attached walls — before you fall in love with something that requires an exchange you can't. Affordability stress in Charlotte is usually a mismatch between budget and unranked priorities, not budget and market.
  3. Check the direction of your life, not the direction of headlines. A market being pricier than it was is not, by itself, a reason to buy or not buy. Your timeline, your stability, and how long you'll stay matter more — and if the buy-at-all question is live for you, the real renting-vs-buying math is the honest place to start.
A sage Charlotte sunroom with filtered light
Affordability in Charlotte is local to the block, not to the city.

So — is Charlotte still affordable?

Relative to the coasts: yes, still, as of mid-2026 — that's why people keep coming. Relative to its own past: no, and it isn't going back. What remains true is more useful than either headline: at nearly every budget, Charlotte still offers a genuinely good life in exchange for a clearly named trade-off. The buyers who struggle here aren't the ones with modest budgets. They're the ones shopping for a city that no longer exists — 2019 prices, 2026 amenities — at any budget.

If you want to know what your number and your priorities actually map to here, take the Move Quiz. Two minutes — budget band, timeline, what you're really solving for — and the conversation starts from your situation instead of a headline.

Take the Move Quiz →

What income do you need to buy a home in Charlotte?

There is no single answer, and anyone who gives you one is selling something. What there is, is a method you can run in ten minutes.

Start from the payment, not the price. Take the monthly number you could pay without resenting it — not the maximum, the comfortable one. Then work backwards with your lender: that payment has to cover principal, interest, property taxes, homeowners insurance, any mortgage insurance, and any association dues. In Charlotte the last four are the ones people forget, and together they routinely move the affordable purchase price by tens of thousands of dollars.

Then check the ratio your lender is actually using. Underwriting compares your total monthly debt to your gross monthly income, and the acceptable ratio moves by loan program. A car payment retired early can change your price band more than a rate change will.

Finally, price the cash, not just the payment. North Carolina asks for a due diligence fee and an earnest money deposit up front, on top of your down payment and closing costs — and the due diligence fee is generally not coming back. An income that supports the monthly payment but not the cash at signing is a very common way to stall out three weeks before closing.

Run those three and you will have a number that belongs to your household rather than to a headline.

Affordability in Charlotte is local to the block, which is a representation problem as much as a math one — here is how to choose an agent who knows the affordable pockets.

Do Charlotte's assistance programs still reach Charlotte prices?

"Is Charlotte still affordable" stops being an abstract question the moment you open a search, set the filter to what you can actually spend, and watch the map empty out. That is the version that gets under your skin — not the headline, the map. And the fear underneath it is rarely that the city is expensive. It is that you waited too long — that the door closed while you were being careful, and that the carefulness itself is what cost you.

I want to take that apart before we go any further, because it is the most common thing I hear and it is mostly not true. The people who waited were not being foolish. Almost all of them were waiting on something real: a job to settle, a relationship to resolve, a number in savings that would let them sleep at night. Waiting for those reasons was the right call at the time and it would be the right call again. What actually changed while you waited is narrower, more specific and far more checkable than "the door closed" — and you can check it yourself, today, in about ten minutes.

Here is how, and it does not involve a single index: look at the price caps the public programs publish, and then see whether homes still exist beneath them. Those caps are the state's and the city's own written definition of what an entry-level home costs here, which makes them the most honest affordability number in circulation — nobody set them to win an argument.

Three published lines, as of 2026:

  1. $495,000 — the sales price cap under the North Carolina Housing Finance Agency's NC Home Advantage umbrella, which is the door to its $15,000 first-time buyer down payment assistance.
  2. $472,030 — the 2026 FHA one-unit mortgage limit for Mecklenburg County. HUD resets these annually by county; confirm yours at HUD's lookup in the week you are actually shopping.
  3. $365,000 — the House Charlotte purchase price cap, and the home must sit inside Charlotte city limits.

The gap between those three tells you something no headline does. The state's line and the federal line sit comfortably above the city's, and the city's line is the one attached to the strictest geography. So the practical affordability question in Charlotte is not "is the city expensive" — it is how much of the city is still reachable under $365,000, and what do you trade to get there. That is a question you can answer yourself in ten minutes with a search, and the answer will be more useful than any index reading.

Two cautions, said plainly. These programs carry income limits, credit minimums and education requirements alongside the price caps, they change, and only a licensed lender can tell you what you may qualify for — I cannot, and neither can any article. And a price cap is a ceiling on eligibility, never a promise that homes beneath it are available where you want to live. But if you want a single reading of whether Charlotte is still affordable, the honest one is this: it is affordable in exactly the places those caps still reach, and the shrinking of that map is what people actually mean when they say the city got expensive.

Sources

  1. Canopy Realtor® Association / Canopy MLS — monthly Charlotte market reports
  2. Federal Housing Finance Agency — House Price Index, Charlotte-Concord-Gastonia metro series
  3. U.S. Census Bureau — American Community Survey, Mecklenburg County housing and income tables
  4. North Carolina Housing Finance Agency — NC Home Advantage Mortgage sales price limit and NC 1st Home Advantage Down Payment terms
  5. DreamKey Partners — House Charlotte program purchase price limit and city-limits requirement
  6. U.S. Department of Housing and Urban Development — FHA Mortgage Limits lookup; Mortgagee Letter 2025-23, 2026 Nationwide Forward Mortgage Loan Limits

Described generally and current as of publication; figures and programs change. Eridania M. Bonilla is a licensed North Carolina broker (NC 359549) with Better Homes and Gardens Real Estate Paracle; each office is independently owned and operated. Equal Housing Opportunity. Not lending, tax or legal advice.

Sixty seconds, no pressure

Which territory are you in?

The Move Quiz maps where you actually are — timeline, budget band, and what you are solving for — in about a minute.

Take the Move Quiz →

Frequently asked

Is Charlotte still affordable in 2026?

Compared to high-cost coastal markets like New York, Los Angeles, or Boston — yes, meaningfully. Compared to Charlotte's own pre-2020 prices — no; years of rapid growth repriced the city permanently. The honest answer depends on your baseline, and the useful question is what your specific budget buys here now.

Why did Charlotte get so expensive?

The simple mechanism: one of the fastest-growing metros in the country absorbed new residents faster than it built homes for them, and construction costs and interest rates rose alongside demand. Prices stepped up across most segments — hardest at the entry level, where the most buyers compete.

Where is it still affordable to buy in Charlotte?

Affordability now lives in trade-offs rather than in a single area: townhomes and condos over detached homes, newer communities farther out over close-in locations, and older homes that need work over updated ones. Every budget still buys well here — what varies is which exchange you make.

Is it cheaper to live in Charlotte than New York or LA?

For housing, yes — the same monthly cost generally carries substantially more space and a different quality of daily life. The gap has narrowed from its peak, but as of mid-2026 it remains real. Run your actual monthly numbers side by side rather than relying on the general reputation.

What salary do you need to buy a house in Charlotte?

It depends far more on your debts, down payment and the property's taxes, insurance and dues than on the purchase price alone. Work backwards from a comfortable monthly payment with a local lender rather than forward from a salary figure you read somewhere.

What is the price limit for down payment assistance in Charlotte?

It depends which program. The North Carolina Housing Finance Agency's NC Home Advantage umbrella caps the sales price at $495,000; House Charlotte caps it at $365,000 and requires the home to be inside Charlotte city limits. FHA's separate 2026 one-unit mortgage limit for Mecklenburg County is $472,030. All three carry their own income, credit and education requirements — a licensed lender is the only one who can tell you what you may qualify for.

A simple Charlotte mudroom with a bench and hooks
Compared to what? is the only version of this question worth asking.
Eridania M. Bonilla, REALTOR®
Your guide
Eridania M. Bonilla
REALTOR® · Better Homes and Gardens Real Estate Paracle

I help Charlotte families buy, move up, and relocate without losing their footing — treating the whole thing as one calm decision instead of a pressured scramble. Twenty-five years in brand and design before real estate taught me that how a place feels is the whole point.

Atención completa en español — escríbeme con confianza.

The quiet letter

One thoughtful note a month

Neighborhood reads, market truth, and the occasional exhale. No noise — unsubscribe anytime.