The Move-Up Move · Charlotte

Signs You Are Ready to Move Up to a Bigger House in Charlotte

Three signs you're ready to move up to a bigger house in Charlotte, plus a three-question self-test on equity, timing and what the next home really costs.
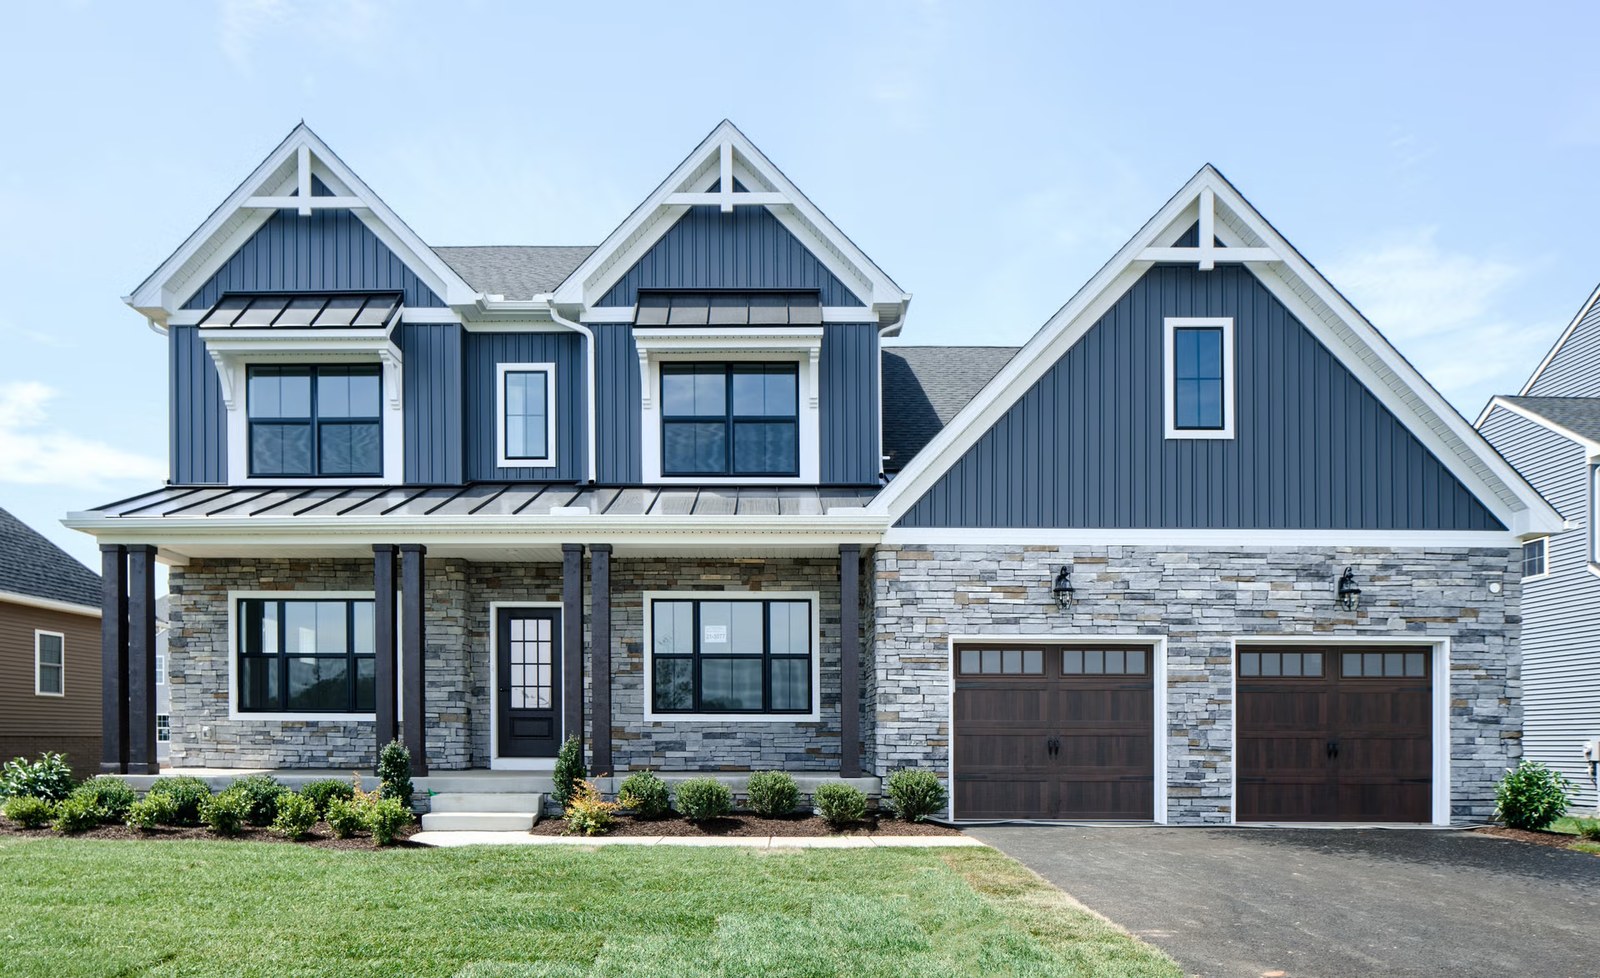
A deep navy board-and-batten Carolina home with a metal roof and stone base
The short answer

You're likely ready to move up in Charlotte when three signals line up: space friction (your home fights your daily life instead of holding it), quiet equity (years of ownership and Charlotte's growth have built value you haven't looked at lately), and a life-stage shift (who lives in the house, and how, has changed since you bought it). What stalls most move-up sellers isn't readiness — it's the fear of carrying two mortgages or landing nowhere in between. That gap is a planning problem with known solutions, not a reason to wait. A calm three-question self-test settles it faster than another year of "maybe next spring."

How do you know when you are ready to move up?

First-time buyers get a clear starting gun: the lease is ending, the rent went up, the math finally tips. Move-up buyers get nothing. No deadline, no notice, no moment where the house formally resigns. So most people in Charlotte who have outgrown their home don't decide to stay — they just never quite decide to go. The question sits in the background for two or three years, surfacing every time the garage won't close or someone takes a work call in the laundry room.

Readiness leaves evidence, though. In my experience it shows up as three signals — and when all three are present, the question has usually already answered itself. You're not deciding whether to move up. You're deciding whether to keep pretending you haven't.

Is your current home actually too small?

Not "the house is small." Friction. The daily, low-grade negotiation with your own floor plan:

  1. Two people who work from home and one door that closes.
  2. A kitchen where two cooks physically cannot pass each other.
  3. The guest room that is also the office that is also the gym, doing none of those jobs well.
  4. Storage arithmetic — the attic is full, the garage stopped holding cars years ago, and every closet requires strategy.

One of these is a quirk. A pattern of them is your home telling you plainly that the life inside it has outgrown the container. And here's the part worth being honest about: some friction is fixable with a renovation, and some isn't. If you're not sure which kind you have, that's its own decision — I map it in Renovate or Sell in Charlotte: The Honest Fork. Friction that traces to the lot, the light, or the location doesn't sand out.

How much equity do you have, really?

Most Charlotte homeowners who bought more than a few years ago are sitting on more equity than they think, for two compounding reasons: they've been paying the mortgage down, and the market has been moving underneath them the whole time. Neither required any action. That's why I call it quiet equity — it accrues silently while you're busy living, and most people's mental number for their home is still anchored to what they paid for it.

The concept that changes the move-up math is this: your equity is your next down payment. You're not starting over the way you did as a first-time buyer, scraping a deposit together from savings. A meaningful share of your next home may already be sitting inside your current one, waiting to be transferred. That's what makes a move-up a different kind of transaction — it's less "buy a bigger house" and more "move your position from one property to another."

I won't put numbers on your situation here, because generic equity math is how people get misled — an online estimate isn't a sale price, and a sale price isn't net proceeds. What your equity actually converts to depends on your payoff, your sale costs, and what your specific home sells for in your specific pocket of Charlotte. (This is exactly the category of thing an algorithm gets wrong — more on that in What Zillow Can't Tell You About Your Charlotte Home.) The point isn't a figure. The point is that the figure probably exists, it's probably larger than your mental anchor, and you deserve to know it before you decide anything.

Has your life changed faster than your house?

You bought the house for a version of your life. Is that still the version you're living?

  1. The starter home bought as a couple that now holds a family.
  2. The "we'll only be here a few years" house, eight years in.
  3. Kids who were toddlers when you closed and now need actual rooms.
  4. A career that moved home permanently and never got a real office.
  5. A next chapter — new marriage, new role, a fresh start — happening inside a house chosen for the last one.

This signal matters because it reframes the decision. A move-up isn't greed for square footage; it's re-aligning the home with who lives there now. Buyers feel vaguely guilty about wanting more house. You shouldn't. The first home was never the destination — it was the first move in a longer sequence (I write about that sequence in First Home vs. Forever Home). Moving up when the life demands it is the sequence working as designed.
A cream Charlotte dining wall with soft morning light
Space friction shows up in your day long before it shows up in your plans.

What stops most people from moving up?

Here's what I actually hear when a ready-by-every-signal homeowner tells me they're waiting: "But what happens in between?" Either version of the nightmare — carrying two mortgages while the old house sits, or selling and having nowhere to go — is enough to keep people in a too-small house for years.

Two honest things about that fear.

First: it's rational. The gap between selling and buying is real, and pretending it isn't would be selling you something. Anyone who tells you "it always works out" is not protecting you.

Second: it's solved. Not softened — solved, with known, boring, established mechanisms. Rent-backs that let you sell and stay put while you close on the next home. Buy-before-you-sell programs and bridge tools that unlock your equity early so you can move once, calmly. Coordinated closings that shrink the overlap to days. The full decision framework — Sell First, Buy First, or the Bridge, and how to choose — is the cornerstone of this series: How to Sell and Buy at the Same Time in Charlotte: The 3 Paths. And if the two-mortgage version is your specific fear, the modern answer to it gets its own deep-dive in Buy Before You Sell: How the Bridge Works in Charlotte.

The fear deserves a plan, not a postponement. Those are different things, and only one of them gets you out of the laundry-room office.

How can you test whether you are ready?

Sit with these for ten quiet minutes. No spreadsheet required.

1. Does your home fight your week? Walk yesterday in your mind. Count the moments of friction — the negotiations, the workarounds, the rooms doing three jobs. If you found more than a couple, that's Signal 1, confirmed by your own Tuesday.

2. Do you actually know your equity number? Not what you paid. Not the app's guess. The realistic what-it-sells-for-minus-what-you-owe number, this season, for your street. If you don't know it, you're making a major life decision with a blindfold on — in either direction. Staying put is also a decision, and it deserves real numbers too.

3. If the in-between were handled — one move, no double mortgage, no scramble — would you go? This is the clarifying question, because it separates the two kinds of "not ready." If the answer is no, you're not ready, and that's a perfectly good answer; enjoy the house. If the answer is yes, then you were never unready. You were unplanned. And a plan is a much easier thing to get than a bigger house is to live without.

What does being ready to move up actually look like?

It isn't a feeling of total certainty — almost nobody gets that, at any price point. It's three signals present, one real equity number known, and a chosen path for the in-between. From there, the move-up stops being a cliff you'd have to jump and becomes a sequence you simply execute: prepare the current home well (the calm four-week version of that is in How to Prep Your Charlotte Home for Sale), price it right for its bracket (what changes at $800K vs. $1M vs. $1.2M), and land once.

If you want to know where you actually stand — which signals are live for you, and which path fits — take the Move Quiz. Two minutes, and it tells you what kind of move-up (or not-yet) you are, so the next conversation starts from your reality instead of your worry. And if it reads "not yet," believe it — that's a real answer, not a failed one.

When the signals line up, the next decision is representation — here is what to look for in an agent for a move-up in Charlotte.

What does the round trip actually cost you?

Here is the question that should decide this and usually never gets asked out loud: moving up is not one transaction, it is two, and you pay for both. Every signal on this page can be lit green and the move can still be wrong, if the round trip costs more than the friction you are trying to escape.

So put the exit on the table. Selling your current Charlotte home carries brokerage compensation, which is negotiable and is usually the largest line; North Carolina's excise tax on the deed, set by statute at one dollar per $500 of the sale price or fraction of it, paid by the seller to the county register of deeds before the deed can be recorded; attorney fees, recording and payoff handling; prorated property taxes; and whatever make-ready, repairs and closing-cost help the sale asks for. Then the purchase side adds its own closing costs, plus North Carolina's due diligence fee and earnest money at contract.

That total is the toll. A move-up that solves a real, daily, structural problem — two people and one door that closes, a life that outgrew a floor plan years ago — clears the toll easily, because you are buying back hours of every week for as long as you live there. A move-up chasing a feeling usually does not.

Which is why "am I ready" and "is it worth it" are different questions, and this is the second one. Run the number before you fall for a listing, not after. Doing it now costs you an afternoon. Doing it later costs you the freedom to change your mind, because by then you will have already decided and will only be looking for permission.

Sources

  1. N.C. Gen. Stat. § 105-228.30 — excise tax on instruments conveying an interest in real property, $1.00 per $500.00 or fraction, paid by the transferor
  2. North Carolina Association of REALTORS® / NC Bar Association — Offer to Purchase and Contract (Form 2-T)
  3. Federal Housing Finance Agency — House Price Index, Charlotte-Concord-Gastonia metro series
  4. Canopy Realtor® Association / Canopy MLS — monthly Charlotte market reports
  5. National Association of REALTORS® — Profile of Home Buyers and Sellers

Described generally and current as of publication; figures and programs change. Eridania M. Bonilla is a licensed North Carolina broker (NC 359549) with Better Homes and Gardens Real Estate Paracle; each office is independently owned and operated. Equal Housing Opportunity. Not lending, tax or legal advice.

Sixty seconds, no pressure

Which territory are you in?

The Move Quiz maps where you actually are — timeline, budget band, and what you are solving for — in about a minute.

Take the Move Quiz →

Frequently asked

How do I know if I'm ready to move up to a bigger home in Charlotte?

Look for three signals: daily space friction (the floor plan fights your routine), meaningful equity built through years of ownership and market growth, and a life-stage shift since you bought. When all three are present and you know your real equity number, you're ready to plan the move — the remaining fear is about the in-between, which is solvable.

Can I use my home equity as the down payment on my next house?

In most move-up scenarios, yes — the equity in your current home becomes the core of the next down payment, either through selling first or through bridge and buy-before-you-sell tools that unlock it early. The exact amount depends on your payoff, sale costs, and actual sale price, so get a real number rather than an online estimate.

What if I can't afford two mortgages at once?

Most move-up sellers can't, and don't have to. Sell First with a negotiated rent-back avoids overlap entirely; the Bridge path compresses it to days. Carrying two full mortgages for months is the outcome bad planning produces, not a requirement of moving up.

Is it a good time to move up in Charlotte?

The better question is whether you're ready — signals, equity, and a chosen path matter more than trying to time the market, because move-up sellers buy and sell in the same market. When your sale and purchase happen in the same conditions, timing the market largely cancels out; planning the gap doesn't.

How much equity do I need to move up to a bigger house in Charlotte?

Enough to cover the down payment and closing costs on the next home after your sale costs come out, with reserves left over. A current net-sheet from your agent and a pre-approval from your lender turn that from a guess into a number.

What does it cost to sell one Charlotte home and buy another?

You pay for two transactions. The sale carries brokerage compensation (negotiable, usually the largest line), North Carolina's excise tax at one dollar per $500 of sale price paid by the seller, attorney and recording fees, prorated taxes, and make-ready or repair costs. The purchase adds its own closing costs plus the due diligence fee and earnest money at contract. A move that solves a real daily structural problem clears that toll; a move chasing a feeling usually does not.

A sage-toned Charlotte sunroom with quiet light
Nobody sends a letter. The signals arrive anyway.
Eridania M. Bonilla, REALTOR®
Your guide
Eridania M. Bonilla
REALTOR® · Better Homes and Gardens Real Estate Paracle

I help Charlotte families buy, move up, and relocate without losing their footing — treating the whole thing as one calm decision instead of a pressured scramble. Twenty-five years in brand and marketing, the last eight in commercial real estate in New York, taught me that how a place feels is the whole point.

Atención completa en español — escríbeme con confianza.

The quiet letter

One thoughtful note a month

Neighborhood reads, market truth, and the occasional exhale. No noise — unsubscribe anytime.